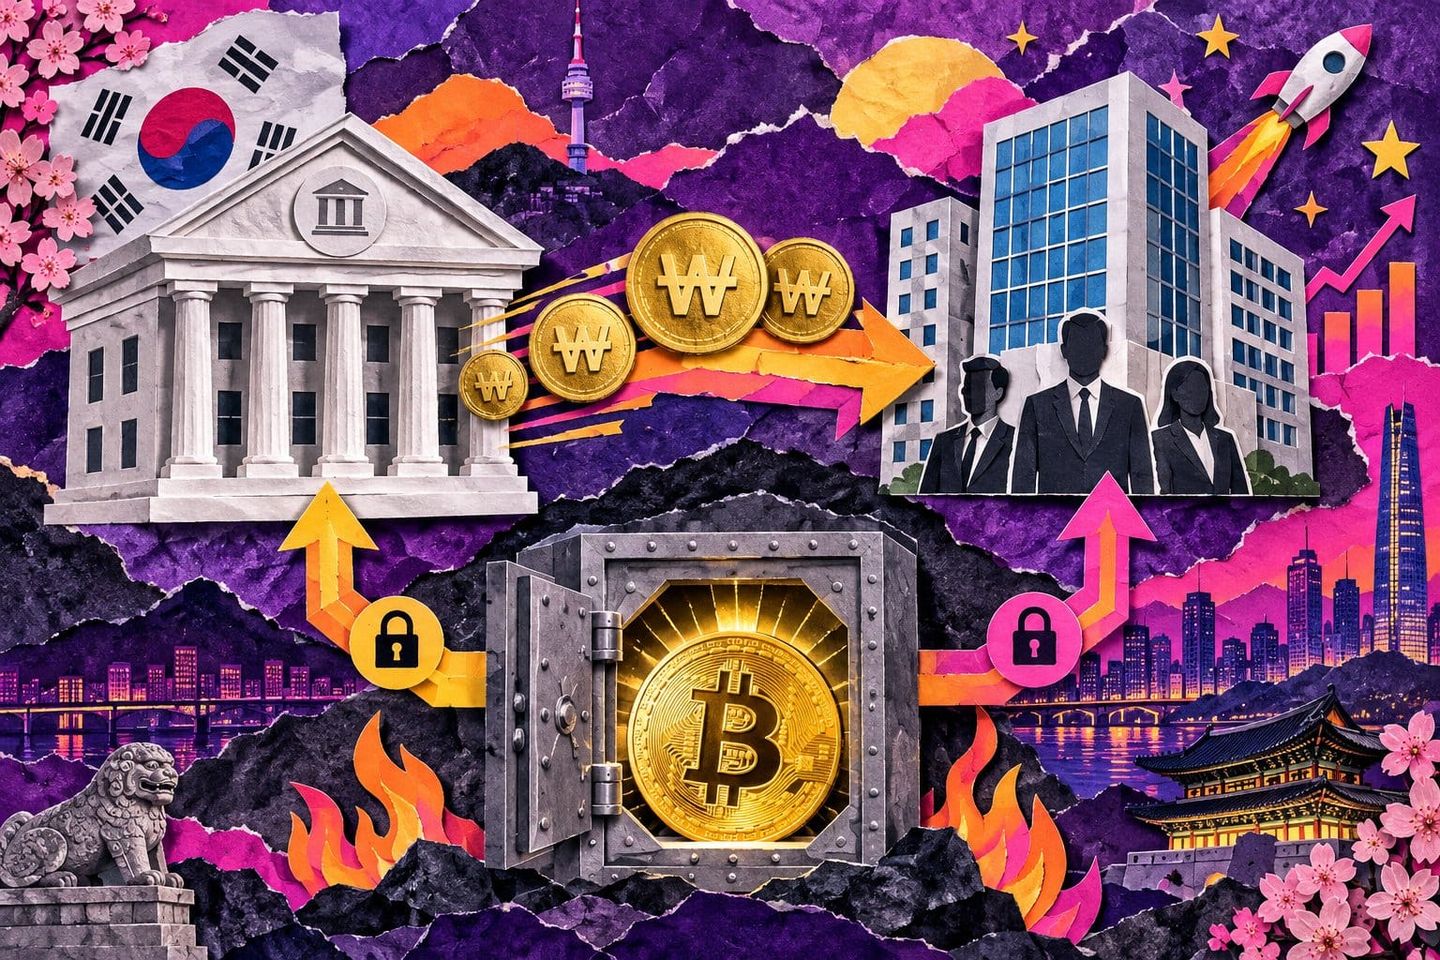
On October 12, 2026, Jeonbuk Bank started lending Korean won to companies that pledge bitcoin as collateral. The bank never holds the coins itself. Korean outlets report that this is the first time a South Korean commercial bank has actually made a loan against a virtual asset.
What did Jeonbuk Bank actually launch?
Jeonbuk Bank is part of JB Financial Group. Its new product is a won-denominated loan for corporate clients only, with bitcoin as the sole accepted collateral . Korean media describe it as the country's first real virtual-asset-backed loan from a commercial bank (source: Ajunews, 2026-10).
Quick Answer: On October 12, 2026, Jeonbuk Bank began lending Korean won to companies against pledged bitcoin. A third-party custodian holds the coins, not the bank. If a borrower defaults, the bank recovers its money through a court-ordered sale under rules that took effect October 1, 2026.
The loan is not just announced. A Jeonbuk Bank official told Jaekyung Ilbo, which broke the story, that a loan "has actually been made." The official would not name the borrowing company . CoinMarketCap carried the news in English the same day.
The product is narrow at launch:
- Who can borrow: companies only. Retail customers are not eligible.
- Collateral: bitcoin only. No ether or other tokens.
- Use of funds: business operating funds only.
- Expansion: the bank will decide later, based on regulation and demand.
These terms are reported by Herald Business .
According to TechM, the bank chose bitcoin because it has the largest market capitalization and trading volume of any digital asset, and the most reliable price benchmark . Korean coverage compares the setup to the stock-backed loans Korean borrowers already use. The company pledges bitcoin it already owns and borrows won against it, without selling the coins.
Why does the bank never touch the bitcoin?
Jeonbuk Bank never holds the pledged bitcoin. It does not control the private keys, it does not own the coins and it has no direct right to manage them . The coins stay with a specialist custody company, inside that company's own management system . The bank works as a lender, not a crypto wallet.
This keeps the bank out of the business that Korean banks have avoided since the 2017–2018 crypto boom: holding digital assets directly. According to TechM, the bank does only two things. It values the collateral and it lends the won . Technical custody and its operational risk sit with the custodian.
The custodian has to meet strict standards. Jaekyung Ilbo reports that it must meet all of the following :
- Be registered as a virtual asset service provider (VASP) under the Act on Reporting and Use of Specific Financial Transaction Information (the Specific Financial Information Act)
- Hold ISMS (information security management system) certification
- Follow the Travel Rule, which requires sender and recipient details to travel with each transfer
- Keep customer assets separate from the company's own assets
- Keep a required share of assets in cold wallets, meaning offline storage
- Carry insurance or hold reserves under the Virtual Asset User Protection Act
CoinMarketCap lists the same requirements . For traders, the rules say a lot about who could do the job. In practice, only a licensed custodian with a full compliance setup could take the work.
One important gap remains. No outlet has named the custodian, and no source we reviewed as of October 13, 2026 identifies it . Until it is named, borrowers and observers cannot check its cold-wallet share, its insurance coverage or its security record. Those details decide how safe the pledged bitcoin really is.
What happens if the borrower defaults?
If a borrower defaults, Jeonbuk Bank does not take the bitcoin. A court-enforced sale converts the pledged coins to cash, and the bank recovers the debt from the proceeds (source: Aju News, 2026-10) . This keeps the bank out of crypto custody even after a default.
The process relies on amended Civil Execution Rules that took effect on October 1, 2026 . According to CoinMarketCap, the amendments cover:
- Seizing and selling virtual assets
- Claims to transfer virtual assets
- Enforcing security rights over virtual assets
The rules took effect only 11 days before the first loan on October 12 . That timing is our own reading, not something the bank has said. It suggests the new court procedures are what made the product legally workable. Without a clear way to sell seized crypto, a lender would have had no reliable way to collect on a default.
The bank says no special permission was needed. Jeonbuk Bank treats the product as ordinary lending under the Banking Act. It is not a designated innovative financial service (Korea's regulatory sandbox) and did not need an exemption . Herald Business notes that no Korean law explicitly bans crypto as loan collateral. Banks stayed away because of government measures from the 2017–2018 boom, which became standard practice rather than law .
"We will pursue new financial demand through innovative products like Korea's first virtual asset collateral loans," — Park Chun-won, President of Jeonbuk Bank (source: Herald Business)
That approach has a limit. Lawmakers are still debating new rules such as the Digital Asset Basic Act. Observers told Jaekyung Ilbo that the bank built the product to fit current law while that debate continues . If new legislation changes the rules on collateral or enforcement, the product may need to be redesigned.
How is the price risk handled, and what is still undisclosed?
Jeonbuk Bank handles bitcoin's price risk with internal stress tests that assume a sharp fall in the price. It values the collateral using a weighted average of prices from several global exchanges, combined with a median of volatility indicators . The bank has not published the terms that would show how much risk it is actually taking on.
According to Herald Business, the bank reviewed loan-to-value (LTV) ratios and margin-call levels for major crypto assets, including bitcoin and ether, while it was designing the product. It also set loan limits and collateral rules for when the pledged bitcoin loses value . Pricing from several exchanges makes the valuation harder to distort with a thin or manipulated quote on any single venue. That matters most for when a margin call is triggered.
Much of the deal is still undisclosed. As of October 12–13, 2026, none of the sources reviewed had published these details :
| Item | Status (Oct 12–13, 2026) |
|---|---|
| Interest rate | Not published |
| Loan limit and LTV | Not published |
| Margin-call threshold | Not published |
| Size of the first loan | Not published |
| Borrower name and sector | Not disclosed |
| Custodian | Not named |
Crypto Briefing presents the loan as the first commercial result of President Park Chun-won's plan to turn Jeonbuk Bank into a digital-asset-focused lender (source: Crypto Briefing, 2026-10). Coverage outside Korea places the product among a small group of banks doing similar lending:
- JPMorgan Chase: institutional bitcoin-backed lending, which CoinMarketCap says began in March .
- Sygnum Bank (Switzerland): offers comparable crypto-backed loans, according to CoinMarketCap.
- Jeonbuk Bank: lends Korean won to companies only, with bitcoin as the only accepted collateral, held by a third-party custodian.
Traders should not read a single loan as large-scale institutional demand. Until the LTV and loan size are published, the deal shows that the legal route works. It does not show how much bitcoin is being used as collateral.
What should traders watch next?
Traders should watch for five signals. Will the bank lend to more types of borrowers? Will it publish the loan terms? Does the Digital Asset Basic Act move forward? Do other Korean banks follow? And is there any measurable market effect? So far, Jeonbuk Bank has only said that wider eligibility depends on how regulation develops and on demand. It has given no timeline .
- Eligibility: Lending is limited to companies, with bitcoin as the only collateral and the funds restricted to business operating costs . A move to retail borrowers or to ether as collateral would be the clearest sign that the product is growing.
- Disclosure: The bank has not named the custodian or published the LTV, the margin-call levels or the interest rate . The LTV and margin-call levels would show how close a price drop can push a loan toward forced liquidation through the courts.
- Legislation and peers: Lawmakers are still debating the Digital Asset Basic Act . If a second Korean bank launches a similar loan, that would suggest the legal route has become standard practice and not a one-off.
In practice, the borrower pledges bitcoin it already holds and borrows won against it. That locks up corporate bitcoin; it does not create new spot selling. Coins would only reach the market if a borrower defaulted and a court-supervised sale followed. No source shows any measurable effect on price yet, so treat claims of market impact as unproven.
Bottom line: the first loan shows the legal route works under the court rules that took effect on October 1, 2026 . Its weight for the market depends on disclosures the bank has not yet made.
Frequently asked questions
Can individuals borrow won against bitcoin at Jeonbuk Bank?
No. At launch, Jeonbuk Bank's bitcoin-backed loan is open only to corporate clients, and the money must be used as business operating funds . Retail customers can't apply. The bank says it will decide later whether to open the loan to more borrowers, based on how regulation develops and how much demand there is (source: TechM, 2026-10).
Who holds the pledged bitcoin?
A third-party specialist custody company holds the pledged bitcoin, not Jeonbuk Bank. The bank has no private keys, no ownership and no direct management rights over the coins (source: Aju News, 2026-10). Jaekyung Ilbo reports that the custodian must meet several conditions :
- It must be a virtual asset service provider registered under the Specific Financial Information Act.
- It must hold ISMS certification and follow the Travel Rule.
- It must keep customer assets separate from its own and hold a required share of them in cold wallets.
- It must carry insurance or reserves under the Virtual Asset User Protection Act.
No source has named the custodian as of October 13, 2026.
What happens to the collateral if the borrower fails to repay?
If the borrower doesn't repay, the bank does not take the bitcoin. Instead, the debt is recovered through court enforcement: the collateral is sold and the bank is paid in cash. This process relies on amended Civil Execution Rules that took effect on October 1, 2026. The amended rules set out how virtual assets can be seized and sold, and how security rights over them are enforced .
Is this a regulatory sandbox product?
No. Jeonbuk Bank says the product is ordinary lending that banks are allowed to do under the Banking Act. It is not a designated innovative financial service (Korea's regulatory sandbox program) and needed no special exemption (source: Aju News, 2026-10). Herald Business notes that no current Korean law explicitly bans using crypto as loan collateral. Banks stayed out because of government measures from the 2017–2018 crypto boom, which became standard practice rather than law .
What are the loan's interest rate and LTV?
They haven't been disclosed. As of October 12–13, 2026, Jeonbuk Bank had not published the interest rate, loan limit, loan-to-value (LTV) ratio or margin-call levels. It also hadn't disclosed the size of the first loan or named the borrower . What is known is that the bank prices the collateral using a weighted average of prices from several global exchanges and ran stress tests that assume a sharp fall in bitcoin's price (source: Jaekyung Ilbo, 2026-10).
Enjoyed this article? Subscribe to get new stories by email whenever they're published.